Market Overview
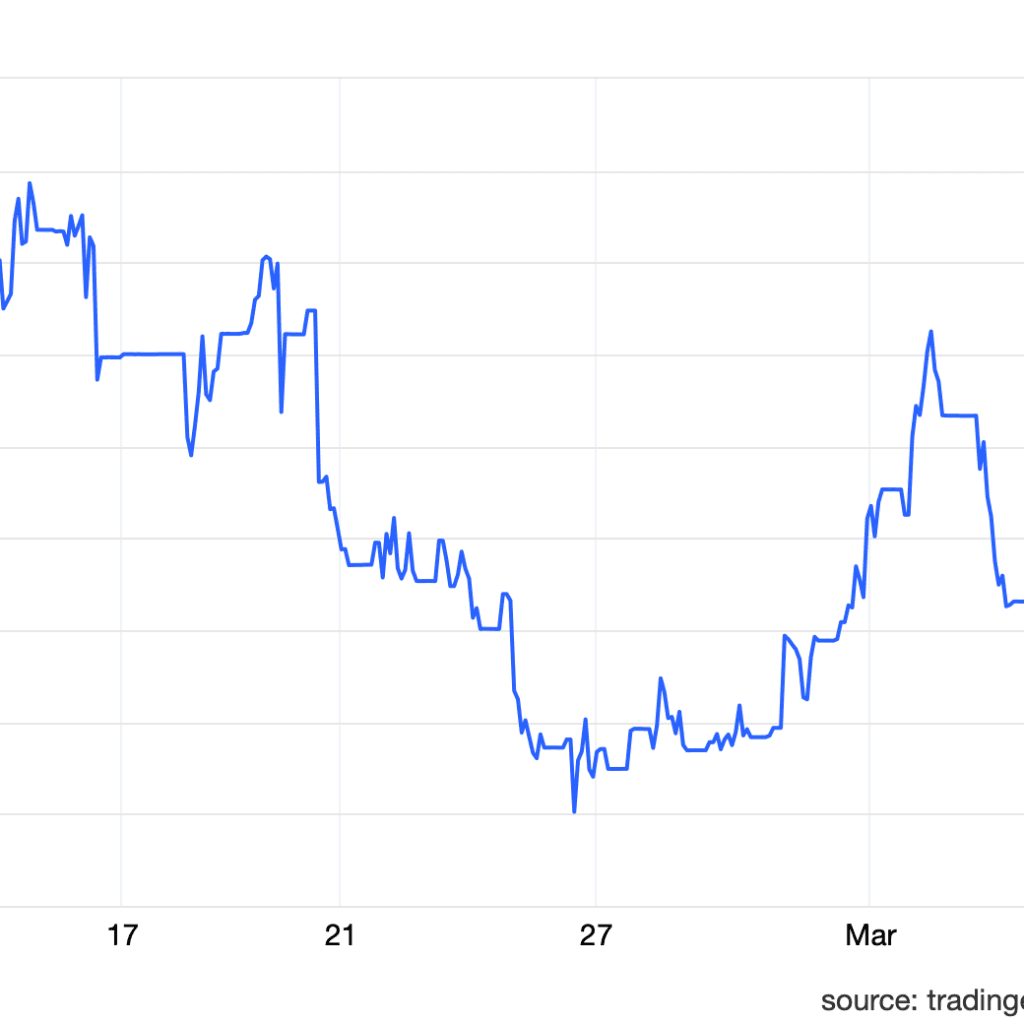
The coffee market has experienced significant volatility this week, with contracts on ICE Futures US and ICE Europe showing notable price movements. The fundamental market conditions remain the same, with low stocks in both producing and consuming countries and ongoing climate-related concerns.
Weather Conditions
Brazil’s coffee sector is facing challenges due to extreme weather conditions. High temperatures during the Brazilian summer have hampered the growth of the new 2025 harvest and severely impacted coffee crop development for 2026. Between January and February, coffee plantations experienced drought and temperatures exceeding 32°C. Temperatures above this disrupts photosynthesis and also reduces leaf production. Cooxupé (Cooperativa Regional de Cafeicultores em Guaxupe) the world’s largest coffee trader, emphasises ongoing climate instability, with some regions experiencing rainfall volumes 60% below historical averages.
Contract Prices
Arabica contracts for May 2025 on ICE Futures US demonstrated substantial price fluctuations. The contracts rose 1,420 points last week, closing at US$ 3.9140. They reached a daily high of US$ 3.9575, with significant price movements throughout the last week. Comparatively, January 2025 saw a substantial rise of 5,650 points, highlighting the market’s volatility.
Robusta contracts on ICE Europe also showed price increases. May 2025 contracts closed at US$ 5,515, rising 118 dollars this last week. The contracts experienced varied daily movements, with January 2025 showing an increase of 889 dollars.
Inventory and Stocks
Certified coffee stocks on ICE Futures have declined, currently standing at 777,708 bags on Friday, 21 March. This represents an increase of 217,081 bags compared to a year ago, with a year-to-date reduction of 205,394 bags. The Brazilian physical market remains calm, with high offer prices preventing the closing of deals. There is interest from buyers for all coffee standards, however, at the price bases offered in the market, sellers retreat and deals are not finalised.
Shipping and Market Dynamics
As of Friday, 21 March shipments were 1,526,707 bags of Arabica coffee, 57,775 bags of Robusta coffee, plus 131,788 bags of insant coffee, totalling 1,718,270 bags shipped, compared to 1,783,338 bags on the same day in February. Certificates of origin requests reached 2,245,925 bags. The Brazilian Real traded at 5.7180 to the US Dollar (on Friday, 21 March), influencing contract pricing in local currency.
Market Outlook
The coffee market continues to face uncertainty. Climate instability, low crop yields, and reduced photosynthesis in coffee plantations suggest potential ongoing challenges. Market participants remain cautious, with Cooxupé noting the difficulty in predicting precise crop impacts until after harvesting and processing.