
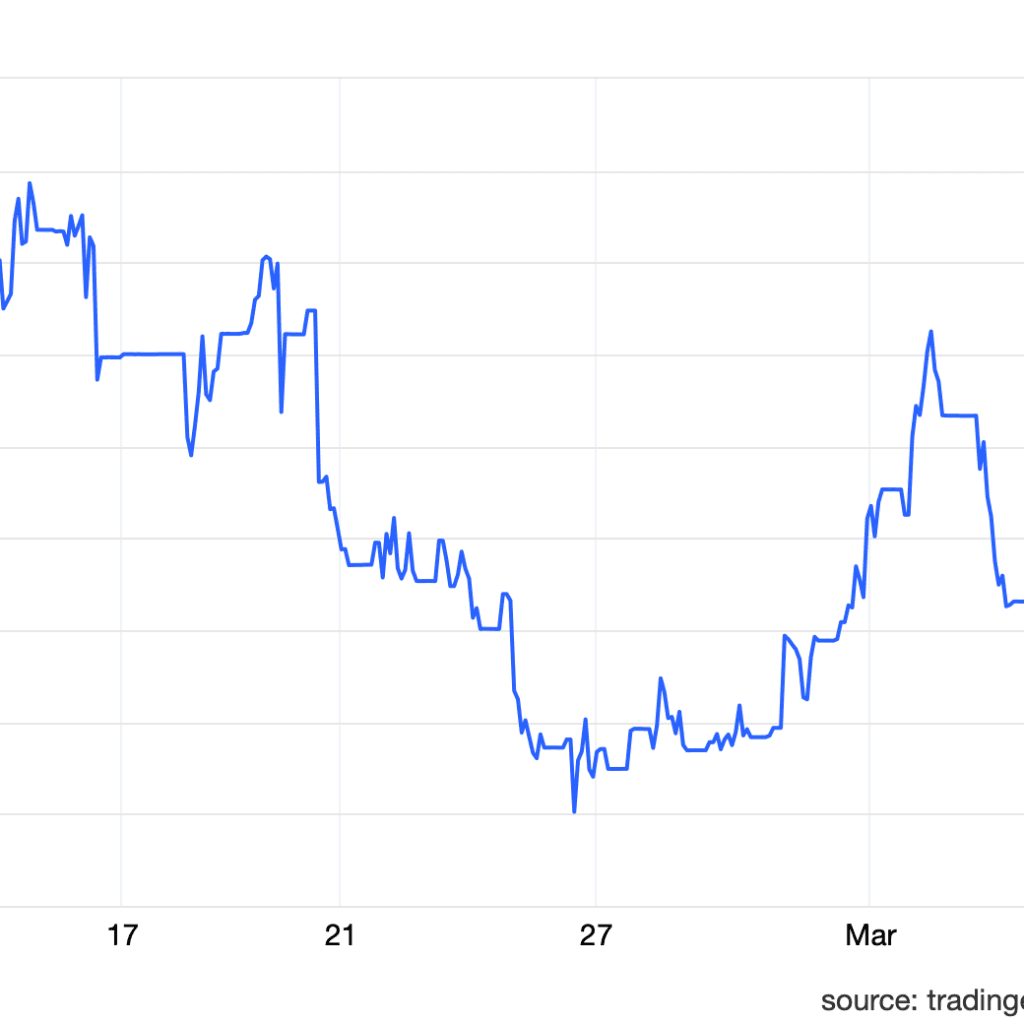
Market Overview: Coffee markets experienced volatile trading this week with strong gains in the first three days followed by declines on Thursday (6/3) and Friday (7/3). Despite the late-week pullback, ICE Futures US and ICE Europe ended positively. Arabica contracts on ICE Futures US rose 1,135 points (3%) for the week, while Robusta contracts on ICE Europe rose $23 (0.43%). Market fluctuations were largely attributed to reactions to unspecified economic and political measures announced by the US president.
Fundamental Factors: Despite price volatility, market fundamentals remain unchanged. Stocks continue to be low in both producing and consuming countries, with ongoing climate problems and extreme weather events occurring globally with no improvement expected in 2025. Brazil faces a tight supply scenario from January to June 2025, with consensus that very little coffee remains from the current harvest, with coffee growers. This limited supply must meet domestic consumption of approximately 1.7 million bags monthly until May, plus export commitments for March through June. The upcoming 2025 Brazilian harvest is not expected to exceed 2024 production levels.
Policy Developments: The Brazilian government announced measures to reduce food prices in the country, including eliminating import tariffs on coffee (previously 9%). However, ABICS (Brazilian Association of the Soluble Coffee Industry) called the measure “futile,” noting that phytosanitary requirements remain in place, limiting coffee imports to just Peru and Vietnam – both facing their export challenges. Vietnam, the world’s largest producer of Robusta coffee, had problems with its harvest, which grew compared to last season but fell short of initial forecasts. At the same time, exports from Peru fell by 77% in volume in January.
Weather Conditions: Dry and hot weather has continued throughout the weekend in coffee-producing areas of São Paulo, Minas Gerais, and interior Bahia, with intensifying heat expected to increase thermal stress for the coffee plantations.
Price Action: Arabica contracts for May 2025 on ICE Futures US fluctuated 1,300 points on Friday, 7 March, reaching a high of $3.9205 before closing at $3.8715, down 275 points. On ICE Europe, Robusta contracts for May 2025 hit a daily high of $5,478 per ton.
Inventory Status: ICE Futures US certified coffee stocks rose by 3,145 bags on Friday, 7 March, totalling up to 797,826 bags. This is an increase of 386,949 bags year-over-year but down 182,141 bags since the beginning of 2025.
Brazilian Market: The physical market remained calm and largely paralysed throughout the past week. February coffee shipments totalled 3,063,778 bags, which is a decrease from January’s 3,858,121 bags. March shipments have reached 267,559 bags (239,192 bags of Arabica coffee, 7,527 bags of Robusta coffee, plus 20,840 bags of instant coffee) as of Friday, the 7th of March.
Currency Impact: The dollar rose 0.52% against the Brazilian real, closing at R$5.7900. On Friday, 7 March, the quotes for delivery in May on the ICE Futures US closed at R$2,944.12 per bag.
Leave A Comment
You must be logged in to post a comment