
Here’s another report dated from last week, Friday, 11 March 2022. The war on eastern Europe of invading Ukraine, caused by Russia, continues. We still have investors who are frightened, and the current market is completely lost and disorientated. It is impossible to evaluate the damage insured in a short, medium, and long-term context in the global as well as the Brazilian economy.

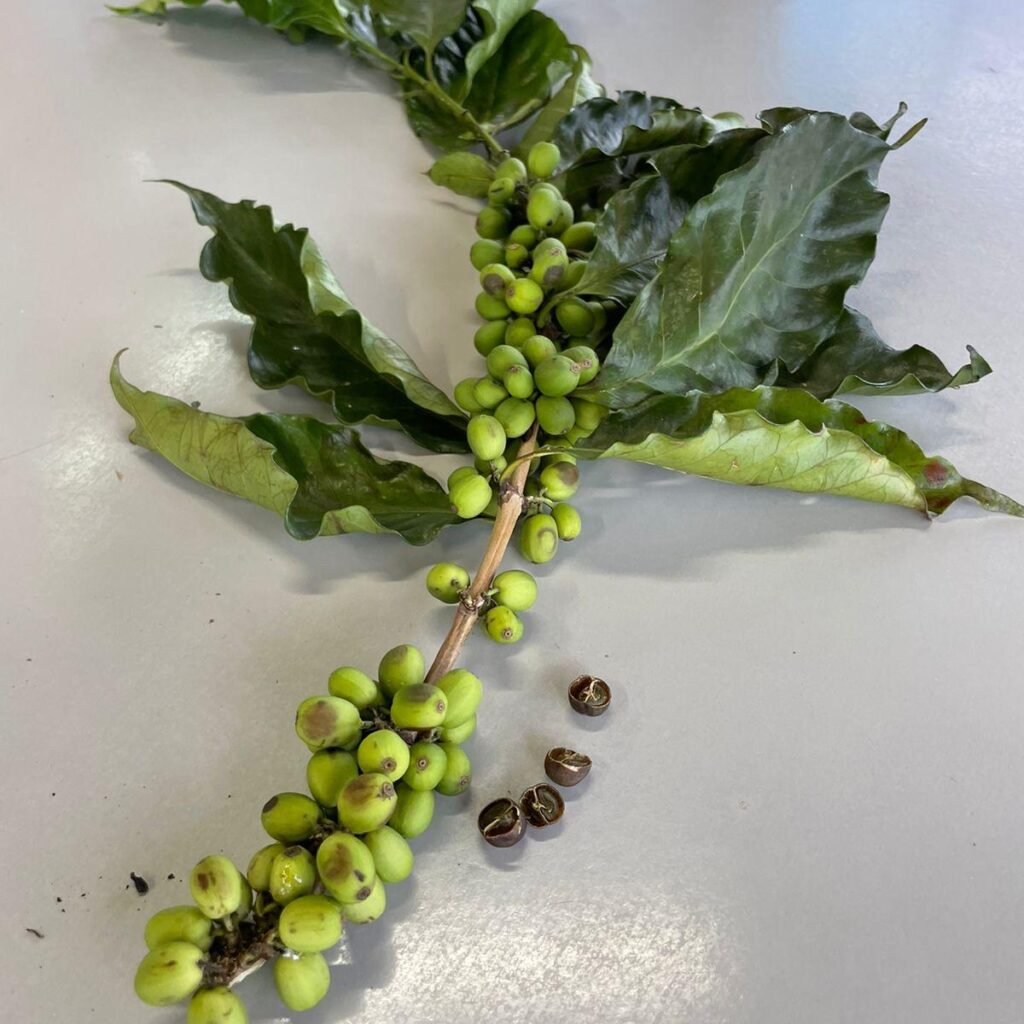
Coffee quotations on the ICE Futures US in New York returned to be quite varied with many ups and downs. At the end of the week, the market closed on a downturn. Analysts talk about the increase in energy prices, caused by the Russian invasion which may destabilise and derail the global economy. This downturn in the economy could cause consumers to reduce their consumption and spending on coffee – bringing a lower average of consumers as they tighten their belts and limit their visits to restaurants and cafés. In our opinion, most coffee farmers won’t harvest for a higher 2-year cycle for 2022 due to huge droughts that occurred in the second half of 2020 and two major frosts in July. This only ended with the beginning of the rains in November 2021. This has brought a lot of concerns to coffee producers in Brazil and has substantially decreased the 2022 crop forecast.
Brazilian giant oil and gas company, PETRONAS, has announced an increase in diesel prices of 24.9% in Brazil. Energy and electricity prices went up last year. The prices of fertilisers, which already started increasing this year, have now skyrocketed. The market has already seen inflation at a minimum of 7% while the SELIC, run by Brazilian journal, Estadão, forecast a minimum of 14%. It is not by mistake that most coffee producers in Brazil have refused to sell their current stocks at the offered prices lately and are instead holding their stocks.
Coffee contracts of ICE Futures in New York had another week of devaluation and closed on Friday, 11 March, with a fall of 225 points (USD 2.2195 per pound). On Thursday, they decreased by 510 points. This week’s balance sheet drop was by 230 points. Last week, the fall altogether was 1440 points. As always, the USD compared to BRL has fluctuated with its ups and downs. Last week, there was a small appreciation of 0.74% where one USD could buy BRL 5.0540. In BRL, low level commodity sacks have been negotiated by BRL 1483.83, compared to the previous week at BRL 1487.90. Two weeks ago, on Friday, they closed at BRL 1506.33.
On Friday, last week, the offers of the buyers were kept at bay as most of the suppliers and producers kept themselves out of the market. The Brazilian physical market has been slow with little business negotiated as the market essentially stopped. On Thursday, the international stocks of certified coffee on the ICE New York, increased by 5,712 bags. They concluded last Thursday at 1,027,688 bags while a year ago they concluded at 1,836,918 bags so there was a drop of stocks by 809,230 bags.
CECAFÉ, Brazilian Agreement of Exporters, released a report that last month in February there were 3,440,963 sacks of 60kg of coffee – approximately a drop by 13.7% (approximately half a million sacks fewer than the same month in 2021). Yet, there were 1.6% more than the previous month of January. There were 3,016,441 sacks of Arabica coffee and 129,809 sacks of Robusta, totalling 3,146,250 bags of green coffee, which added to 291,746 bags of instant coffee and 2,967 bags of roasted beans, totalling altogether 3,440,963 sacks.
Up to the 11th of March, the shipments exported from Brazil were 438,226 sacks of Arabica coffee, 18,399 sacks of Robusta beans, 36,373 bags of instant coffee, totalling 492,998 bags, against 569,399 bags on the same day in the month of February. Up to the 11th of March, the requests for certified of origin totalled about 1,065,683 sacks against 1,122,878 sacks on the same day in the previous month.
We look to the beginning of the week, with Monday the 14th and Tuesday the 15th of March with further losses on the coffee market. This is due to decreasing prices caused by the war in Ukraine which keeps pushing the prices down with fear of high inflation and squeeze on consumer purchasing power. Our forecast is that the price will go up until Easter due to the basics of the global economy. Though, the war in Ukraine has shaken this up a bit. If we start seeing the beginning of the harvest at the end of April/beginning of May then we will see that prices will ease further, subject to major catastrophic climate disasters in Brazilian wintertime. Hopefully there will be more price stability with a peace agreement between Russia and Ukraine. We hope that Brazil will manage a successful harvest during the summertime in the northern hemisphere and we can start to have a bit more stability in the nearby future.
I wish you all the very best!
Thank you very much,
Leave A Comment
You must be logged in to post a comment