
Global Market Impact
President Trump’s recently announced “reciprocal tariffs” have caused significant market turmoil globally, with US stocks losing $5.4 trillion over two days since it was announced. The minimum tariff on Brazilian exports to the US is set at 10%, while China faces 34%, the EU 20%, Vietnam 46%, and Indonesia 32%. These measures have prompted retaliatory action from China, intensifying concerns about a possible global recession. This has had a major impact on commodity prices in general, putting pressure on the currency rates of countries focused on exporting raw materials.
Coffee prices on the London and New York stock exchanges have been dragged down in this market “tsunami,” though underlying fundamentals suggest potential stability due to low global stocks and ongoing climate challenges affecting production worldwide.
Market Performance
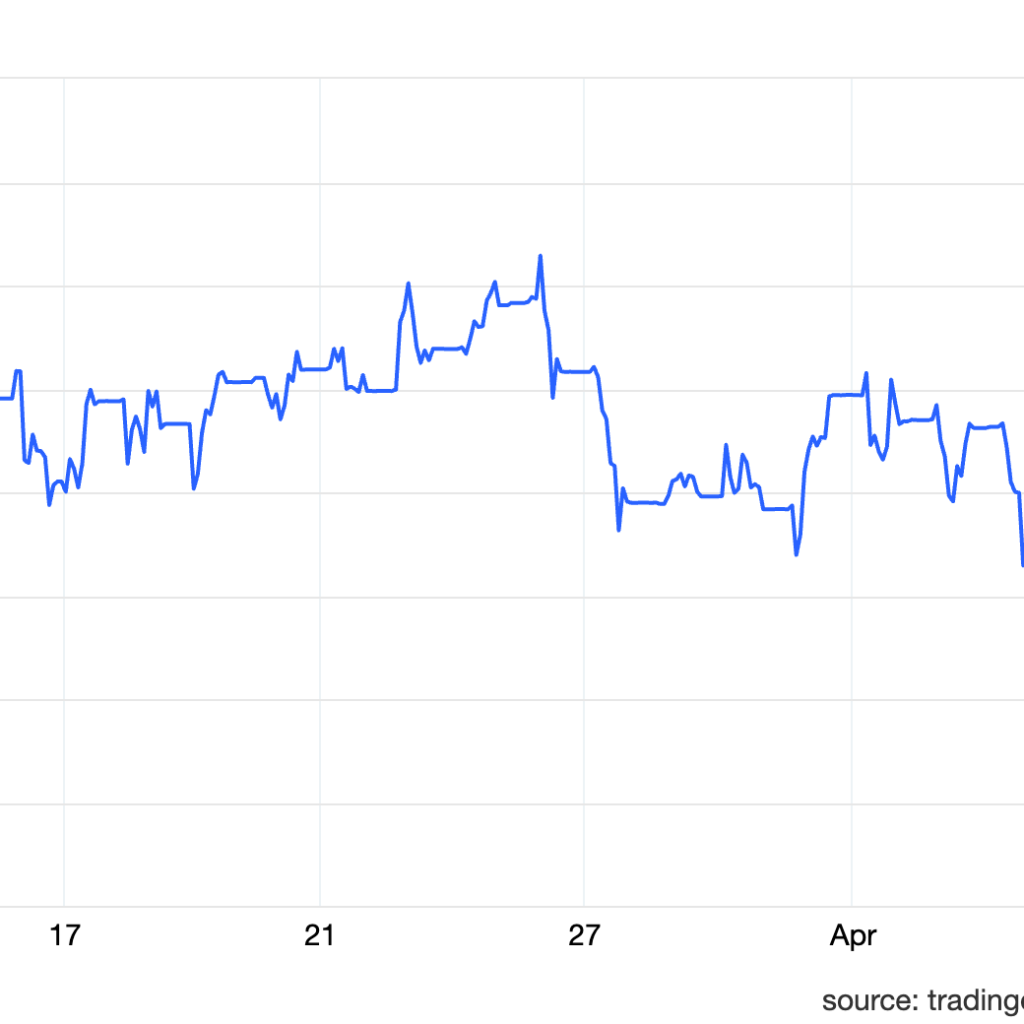
Arabica contracts due in May on ICE Futures US closed at $3.6570, down 1,955 points on Friday, 4 April, with weekly losses of 1,420 points. These contracts showed extreme volatility with a 2,445-point fluctuation range last Friday. Despite recent declines, Q1 2025 still shows an impressive gain of 6,490 points.
Robusta contracts for May on ICE Europe closed at $5,112 per ton, down $259, with weekly losses of $225 on Friday, 4 April. Q1 2025 maintains a gain of $464 per ton despite recent market pressure.
Inventory & Currency Developments
Certified coffee stocks on ICE Futures decreased by 11,099 bags to 771,014 bags, representing a year-over-year increase of 142,797 bags but a significant Q1 2025 reduction of 209,491 bags.
The US dollar surged 3.70% against the Brazilian real, closing at R$5.8360, further complicating the market landscape for Brazilian producers. In reais, May contracts on ICE Futures US closed on Friday, 4 April at R$2,823.15 per bag.
Brazilian Market Activity
The Brazilian physical market did not open on the 3rd and 4th of April, it was paralysed. There is interest from buyers for all coffee standards, however, based on the prices offered on the market, sellers are reluctant and few deals are concluded. Sales volume continues below necessary levels to meet domestic consumption and export demands.
Shipments
As of Friday, 4 April, March coffee shipments totalled 3,251,768 bags (2,791,975 Arabica, 138,582 Robusta, 321,211 instant coffee), exceeding February’s comparable figure. Certificates of origin requests for March reached 3,441,014 bags. Up to the 4th of April, April shipments have begun with 106,461 total bags, while certificates of origin requests for April total 471,021 bags, down from March’s comparable figure of 627,332 bags.
Outlook
The coffee market outlook remains uncertain as global trade rules undergo profound changes. The impact of these “reciprocal tariffs” requires further monitoring, particularly as Brazilian green coffee exports to the US support thousands of American jobs in processing and marketing.
Leave A Comment
You must be logged in to post a comment